Using Time-Series Anomaly Detection Approach for Identifying Arbitrage Opportunities
DOI:
https://doi.org/10.22452/mjs.vol45sp2.2Keywords:
anomaly detection, machine learning, pairs trading, Philippine stocks, statistical arbitrageAbstract
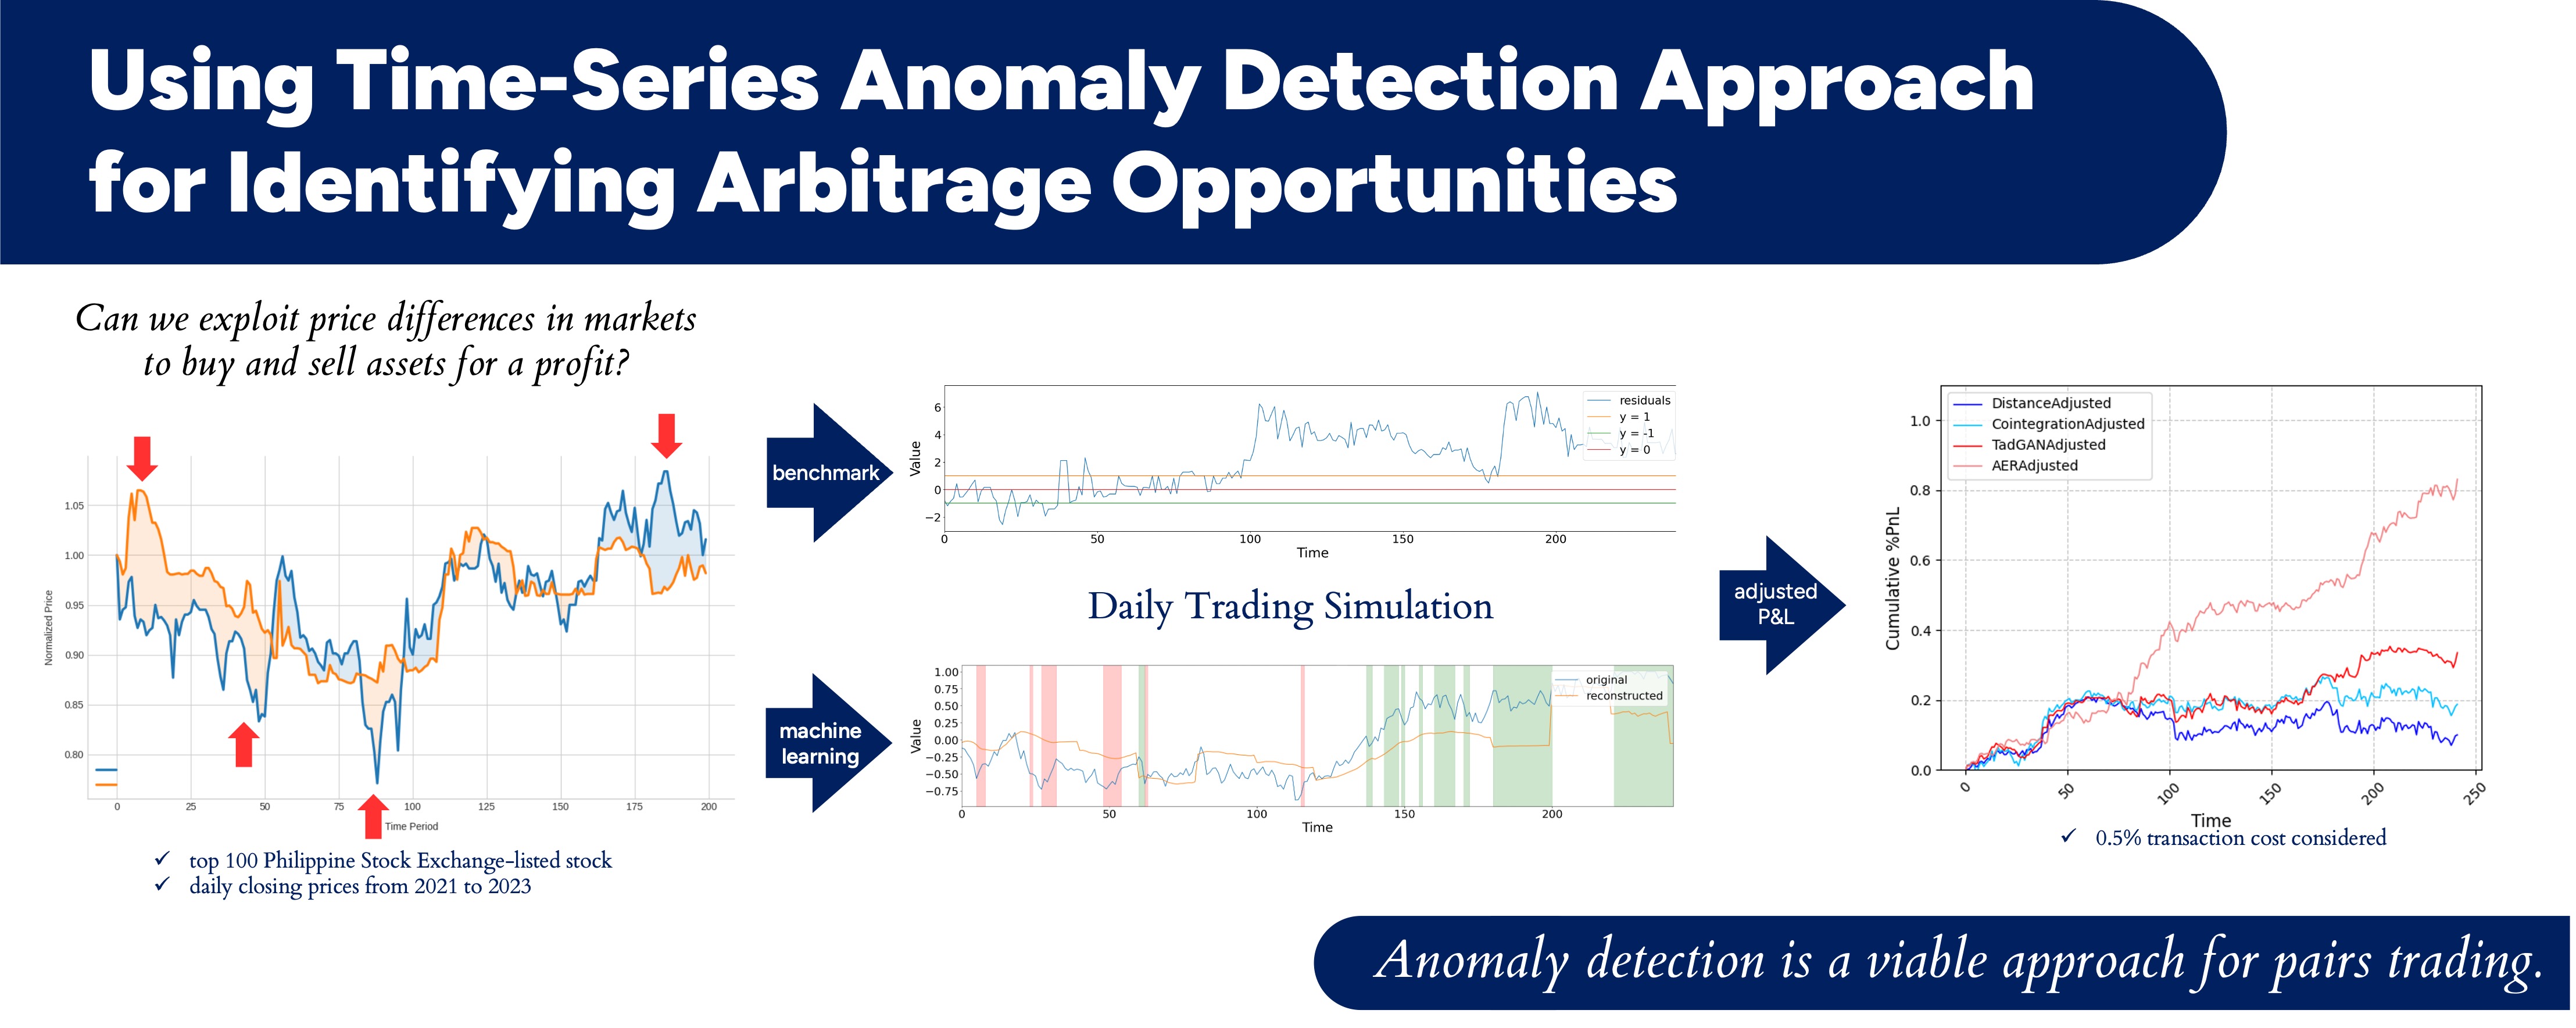
Since market anomalies are tedious and difficult to manually identify, the use of anomaly detection techniques to find statistical arbitrage opportunities is becoming increasingly popular. As such, this study compares the performance of different pairs trading strategies on the top 100 Philippine stocks listed on the Philippine Stock Exchange to assess the feasibility of using machine learning-based anomaly detection models. Specifically, time series anomaly detection through generative adversarial networks and auto-encoder with regression were employed to detect statistical arbitrage opportunities. The comparison across the strategies was limited to the top five cointegrated pairs (of order one) with the smallest sum of squared residuals. Results show that, even after accounting for transaction costs, AER outperformed the benchmarks (distance and cointegration approaches) by a wide margin, while TadGAN achieved a slightly better performance than the benchmarks. These findings suggest that anomaly detection models have the potential to yield higher profits than conventional approaches.
References
Ajewole, K., Adejuwon, S., & Jemilohun, V. (2020). Test for stationarity on inflation rates in Nigeria using augmented Dickey Fuller test and Phillips-Persons test. IOSR Journal of Mathematics, 16(3), 11–14.
Aquino, R. (2002). Informational efficiency characteristics of the Philippine stock market (Technical Report). UP College of Business Administration.
Canady, T. S. (2022). Making sense of market anomalies.
Carrasco Blázquez, M., De la Orden De la Cruz, C., & Prado Rom´an, C. (2018). Pairs trading techniques: An empirical contrast. European Research on Management and Business Economics, 24(3), 160–167.
Fernández-Pérez, A., de las Nieves López-García, M., & Requena, J. P. R. (2020). On the sensibility of the pairs trading strategy: The case of the FTS Stock Market Index. Studies of Applied Economics, 38(3).
Gatev, E., Goetzmann, W., & Rouwenhorst, K. G. (2006). Pairs trading: Performance of a relative-value arbitrage rule. The Review of Financial Studies, 19(3), 797–827.
Geiger, A., Liu, D., Alnegheimish, S., Cuesta-Infante, A., & Veeramachaneni, K. (2020). TadGAN: Time series anomaly detection using generative adversarial networks.
Girard, E., & Biswas, R. (2007). Trading volume and market volatility: Developed versus emerging stock markets. Financial Review, 42(3), 429–459.
Krauss, C. (2017). Statistical arbitrage pairs trading strategies: Review and outlook. Journal of Economic Surveys, 31(2), 513–545.
Moura, M. (2010). Testing the Taylor model predictability for exchange rates in Latin America. Open Economies Review, 21, 547–564.
Nakashima, T., & Yairi, T. (2023). Assessing the performance of transformer for time series anomaly detection. In PHM Society Asia-Pacific Conference (Vol. 4).
Rad, H., Low, R. K. Y., & Faff, R. (2016). The profitability of pairs trading strategies: Distance, cointegration and copula methods. Quantitative Finance, 16(10), 1541–1558.
Tallboys, J., Zhu, Y., & Rajasegarar, S. (2022). Identification of stock market manipulation with deep learning. In Advanced Data Mining and Applications (pp. 408–420). Springer International Publishing.
Ullah, F., Ullah, S., Srivastava, G., & Lin, J. C.-W. (2024). IDS-INT: Intrusion detection system using transformer-based transfer learning for imbalanced network traffic. Digital Communications and Networks, 10(1), 190–204.
Wong, L., Liu, D., Berti-Equille, L., Alnegheimish, S., & Veeramachaneni, K. (2022). AER: Auto-encoder with regression for time series anomaly detection.
Downloads
Published
Issue
Section
License
Copyright (c) 2026 Malaysian Journal of Science (MJS)

This work is licensed under a Creative Commons Attribution-NonCommercial 4.0 International License.
Transfer of Copyrights
- In the event of publication of the manuscript entitled [INSERT MANUSCRIPT TITLE AND REF NO.] in the Malaysian Journal of Science, I hereby transfer copyrights of the manuscript title, abstract and contents to the Malaysian Journal of Science and the Faculty of Science, University of Malaya (as the publisher) for the full legal term of copyright and any renewals thereof throughout the world in any format, and any media for communication.
Conditions of Publication
- I hereby state that this manuscript to be published is an original work, unpublished in any form prior and I have obtained the necessary permission for the reproduction (or am the owner) of any images, illustrations, tables, charts, figures, maps, photographs and other visual materials of whom the copyrights is owned by a third party.
- This manuscript contains no statements that are contradictory to the relevant local and international laws or that infringes on the rights of others.
- I agree to indemnify the Malaysian Journal of Science and the Faculty of Science, University of Malaya (as the publisher) in the event of any claims that arise in regards to the above conditions and assume full liability on the published manuscript.
Reviewer’s Responsibilities
- Reviewers must treat the manuscripts received for reviewing process as confidential. It must not be shown or discussed with others without the authorization from the editor of MJS.
- Reviewers assigned must not have conflicts of interest with respect to the original work, the authors of the article or the research funding.
- Reviewers should judge or evaluate the manuscripts objective as possible. The feedback from the reviewers should be express clearly with supporting arguments.
- If the assigned reviewer considers themselves not able to complete the review of the manuscript, they must communicate with the editor, so that the manuscript could be sent to another suitable reviewer.
Copyright: Rights of the Author(s)
- Effective 2007, it will become the policy of the Malaysian Journal of Science (published by the Faculty of Science, University of Malaya) to obtain copyrights of all manuscripts published. This is to facilitate:
- Protection against copyright infringement of the manuscript through copyright breaches or piracy.
- Timely handling of reproduction requests from authorized third parties that are addressed directly to the Faculty of Science, University of Malaya.
- As the author, you may publish the fore-mentioned manuscript, whole or any part thereof, provided acknowledgement regarding copyright notice and reference to first publication in the Malaysian Journal of Science and Faculty of Science, University of Malaya (as the publishers) are given. You may produce copies of your manuscript, whole or any part thereof, for teaching purposes or to be provided, on individual basis, to fellow researchers.
- You may include the fore-mentioned manuscript, whole or any part thereof, electronically on a secure network at your affiliated institution, provided acknowledgement regarding copyright notice and reference to first publication in the Malaysian Journal of Science and Faculty of Science, University of Malaya (as the publishers) are given.
- You may include the fore-mentioned manuscript, whole or any part thereof, on the World Wide Web, provided acknowledgement regarding copyright notice and reference to first publication in the Malaysian Journal of Science and Faculty of Science, University of Malaya (as the publishers) are given.
- In the event that your manuscript, whole or any part thereof, has been requested to be reproduced, for any purpose or in any form approved by the Malaysian Journal of Science and Faculty of Science, University of Malaya (as the publishers), you will be informed. It is requested that any changes to your contact details (especially e-mail addresses) are made known.
Copyright: Role and responsibility of the Author(s)
- In the event of the manuscript to be published in the Malaysian Journal of Science contains materials copyrighted to others prior, it is the responsibility of current author(s) to obtain written permission from the copyright owner or owners.
- This written permission should be submitted with the proof-copy of the manuscript to be published in the Malaysian Journal of Science
Licensing Policy
Malaysian Journal of Science is an open-access journal that follows the Creative Commons Attribution-Non-commercial 4.0 International License (CC BY-NC 4.0)
CC BY – NC 4.0: Under this licence, the reusers to distribute, remix, alter, and build upon the content in any media or format for non-commercial purposes only, as long as proper acknowledgement is given to the authors of the original work. Please take the time to read the whole licence agreement (https://creativecommons.org/licenses/by-nc/4.0/legalcode ).